Compound interest is the closest thing to a superpower in personal finance. Your money earns returns, and then those returns earn returns too. Left alone long enough, the growth stops looking like a line and starts looking like a hockey stick.
This guide shows exactly how it works — with real numbers for a £300-a-month saver — and how to calculate your own scenario in seconds.
What is the difference between simple and compound interest?
Suppose you invest £10,000 at 6% a year.
Simple interest pays 6% on the original £10,000 only — £600 a year, forever. After 20 years you have £10,000 plus 20 × £600 = £22,000.
Compound interest pays 6% on everything in the pot, including previous interest. Year one you earn £600. Year two you earn 6% of £10,600 = £636. The annual payout creeps up every year, and after 20 years you have £32,071 — the same rate, the same period, £10,000 more.
That gap is the entire reason people say "start early".
What is the compound interest formula for monthly savings?
For a one-off lump sum: A = P × (1 + r)n, where P is your starting amount, r the growth rate per period, and n the number of periods.
For monthly contributions like the example below, each payment compounds for a different length of time — doing this by hand is painful. That's exactly what the compound interest calculator is for: enter a starting amount, monthly contribution and rate, and it projects the full curve year by year.
What does £300 a month become in 10, 20, or 30 years?
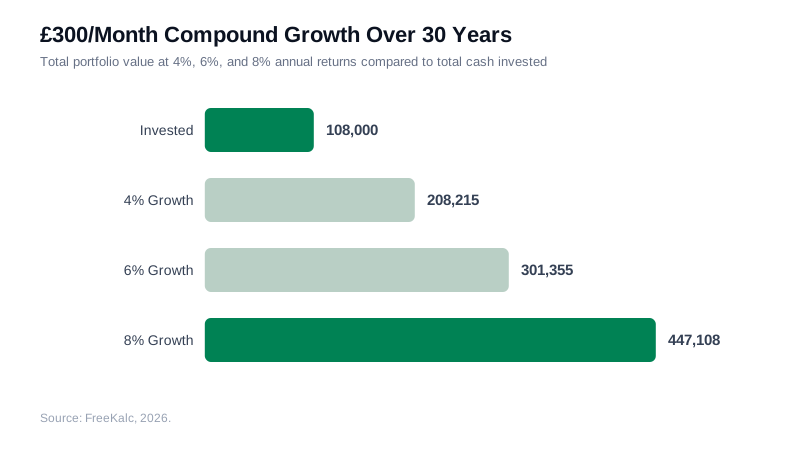
Here are the real numbers for someone saving £300 every month, with no starting lump sum, at three growth rates:
| Years | Invested | At 4% | At 6% | At 8% |
|---|---|---|---|---|
| 10 | £36,000 | £44,175 | £49,164 | £54,884 |
| 20 | £72,000 | £110,032 | £138,612 | £176,706 |
| 30 | £108,000 | £208,215 | £301,355 | £447,108 |
Three things jump out:
- The last decade does the heavy lifting. At 8%, the pot grows by £270,000 between year 20 and year 30 — more than double the growth of the first 20 years combined.
- Growth outpaces your own deposits. At 8% over 30 years, you contribute £108,000 and the market adds £339,108 on top.
- Rate matters as much as time. The 30-year difference between 6% and 8% is nearly £146,000 — from the same £108,000 of deposits.
How does the Rule of 72 work for compound interest?
A quick mental shortcut: divide 72 by your annual growth rate to estimate how long money takes to double. At 6%, a lump sum doubles roughly every 12 years (72 ÷ 6). At 8%, every 9 years. It's not exact, but it's remarkably close for rates between 4% and 12% — handy for sanity-checking any investment pitch that sounds too good.
Where does compound interest apply in everyday personal finance?
Pensions. A workplace pension is compound interest with a booster: employer contributions and tax relief increase the monthly amount going in, so the curve starts even higher. US readers get the same effect from a 401(k) with an employer match — never leave matching money on the table.
ISAs and index funds. A stocks & shares ISA holds funds in a tax-free wrapper, so compounding isn't slowed down by tax on dividends or gains.
Debt — in reverse. The same maths powers credit cards and payday loans. A 39.9% APR card compounds against you: 72 ÷ 40 means the balance tries to double roughly every two years if unpaid. Compounding is a tool; it doesn't care which side you're on.
How can you achieve a 6% to 8% annual investment return?
Nobody guarantees returns, but long-run global stock market growth has historically landed near this range before inflation. The practical takeaways most independent sources agree on:
- Use low-cost index funds rather than stock-picking — fees compound against you just as surely as returns compound for you.
- Automate the monthly contribution so you don't rely on willpower.
- Don't panic-sell in downturns; missing the recovery destroys more compounding than the crash itself.
This site doesn't give financial advice — the numbers above are illustrations, not predictions.
Run your own numbers
Frequently asked questions
What does £300 a month become after 20 years at 6% interest?
Investing £300 a month at a 6% annual return grows to £138,612 after 20 years. Over that time, your out-of-pocket contributions total £72,000, while compound interest generates £66,612 in investment returns. Compounding monthly continuously reinvests your earnings so your portfolio accelerates over time.
What does £300 a month turn into after 30 years at 8%?
At an 8% annual return, saving £300 every month accumulates to £447,108 over 30 years. You deposit £108,000 in personal savings, while market growth adds £339,108 on top. The final decade provides £270,402 of that growth, demonstrating how compounding momentum expands exponentially in later years.
How does the Rule of 72 calculate investment doubling time?
The Rule of 72 provides a rapid mental estimate for how fast money doubles by dividing 72 by your annual interest rate. For example, at a 6% annual growth rate, a lump sum doubles in roughly 12 years (72 divided by 6), whereas at 8% it takes about 9 years.
What is the difference in returns between simple and compound interest on £10,000?
On a £10,000 lump sum over 20 years at 6%, simple interest yields £22,000 because interest pays on the principal only. Compound interest calculates growth on previous interest as well, producing £32,071. That creates a £10,071 advantage for compound interest on the exact same underlying investment.
Related tools
- Compound interest calculator — see growth over any period
- Loan calculator — monthly payments and total interest
- Mortgage calculator — what a home loan really costs
- How much mortgage can I afford? — UK affordability worked through