How much is £60,000 a year after tax in the UK?
| Pay period | Take-home pay |
|---|---|
| Per year | £45,357.40 |
| Per month | £3,779.78 |
| Every 4 weeks | £3,489.03 |
| Per week | £872.26 |
| Per day (260 working days) | £174.45 |
| Per hour (37.5-hour week) | £23.26 |
Try it: what would you take home on £60,000?
Adjust the salary or student loan option below — every figure uses the same 2026/27 tax and National Insurance model as this page.
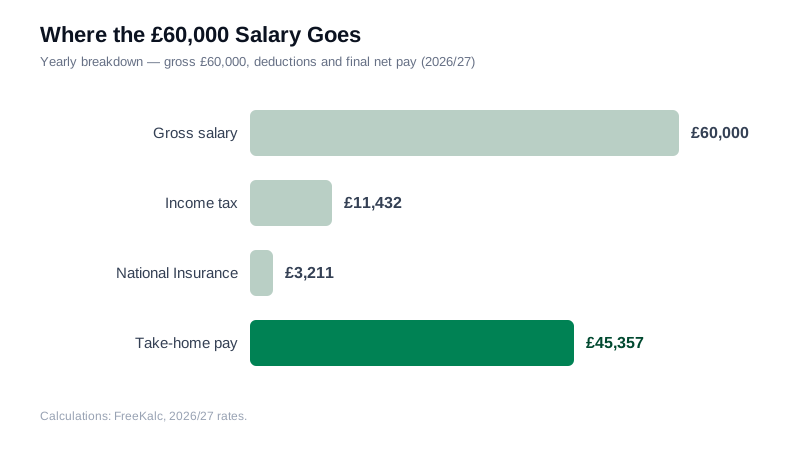
From £60,000 gross, you keep £45,357.40 — about 76% of everything you earn. The rest goes to income tax (£11,432) and National Insurance (£3,211).
Where does the money go — tax, NI and take-home?
| Deduction | Amount per year |
|---|---|
| Gross salary | £60,000.00 |
| Personal allowance | £12,570.00 tax-free |
| Income tax (20% basic, 40% higher) | −£11,432.00 |
| National Insurance (8% to £50,270, then 2%) | −£3,210.60 |
| Take-home pay | £45,357.40 |
You are earning in the higher-rate band: extra pay is taxed at 40% with 2% NI added, a 42% marginal rate.
Student loan deductions on 60k: all five plans
On top of tax and NI, student loan repayments reduce your pay further. Your plan determines how much less you take home at this salary:
| Plan | Repayment threshold | Rate | Annual deduction |
|---|---|---|---|
| Plan 1 | £26,900.00 | 9% | £2,979.00 |
| Plan 2 | £29,385.00 | 9% | £2,755.35 |
| Plan 4 | £33,795.00 | 9% | £2,358.45 |
| Plan 5 | £25,000.00 | 9% | £3,150.00 |
| Postgraduate | £21,000.00 | 6% | £2,340.00 |
Plan 5 and postgraduate loans bite earliest (thresholds £25,000 and £21,000). If you are on Plan 4 (Scottish loans) your threshold is £33,795. Borrowers with both Plan 1 and Plan 2 loans repay both plans once they pass the Plan 1 threshold.
What a pay rise actually pays you
Here is what typical raises actually leave in your pocket at this salary, calculated with the 2026/27 bands, the allowance taper and both NI rates:
| Pay rise | Tax + NI on the rise | Extra take-home |
|---|---|---|
| +£1,000 (to £61,000) | −£420.00 | +£580.00 net |
| +£2,500 (to £62,500) | −£1,050.00 | +£1,450.00 net |
| +£5,000 (to £65,000) | −£2,100.00 | +£2,900.00 net |
| +£10,000 (to £70,000) | −£4,200.00 | +£5,800.00 net |
A £2,500 rise is worth about £120.83 extra a month. Remember the marginal rate on your next pound is 42%.
Monthly budget on 60k: the 50/30/20 rule
A common budgeting split for a take-home of £3,779.78 a month:
| Category | Share | Monthly amount | Typical use |
|---|---|---|---|
| Needs | 50% | £1,889.89 | Rent, utilities, food, transport, minimum debt payments |
| Wants | 30% | £1,133.93 | Dining out, streaming, gym, hobbies, travel |
| Savings & debt payoff | 20% | £755.96 | Emergency fund, pension top-ups, overpaying debt |
Mortgage lenders typically cap borrowing near 4.5× gross salary, so a 60k income supports roughly a £270,000 mortgage — enough for a first flat in most regional cities with a 10% deposit.
What about Scotland?
Scottish rates differ: a 19% starter band, then 20% and a 21% intermediate band, with 42% and 45% higher rates (48% above £75,000). At this salary the difference is only a few pounds a week. National Insurance stays the same across the UK.
Does a pension change this?
The figures above assume no pension contributions. Auto-enrolment takes a minimum 5% of your salary pre-tax, but because contributions reduce taxable pay the hit to take-home is only about £180.00 a month at the 5% minimum — and your employer adds at least 3% on top.
Is 60k a good salary in the UK?
£60,000 is around the 82nd percentile of UK full-time earners — over £22,500 above the median of £37,430 (ONS, 2026), and a typical senior professional or middle-management salary.
£3,780 a month is the classic senior-professional budget: two-bed flat or small house share of the mortgage market, car, and four-figure annual holiday spend without stress.
Frequently asked questions
Is £60,000 a year a good salary in the UK in 2026?
£60,000 is around the 82nd percentile of UK full-time earners — over £22,500 above the median of £37,430 (ONS, 2026), and a typical senior professional or middle-management salary. Against a median of about £37,430, this is well above the typical UK wage.
How much is £60,000 a year per month after tax?
Take-home pay is £45,357.40 a year, which is £3,779.78 per month after income tax and National Insurance. With a student loan the figure is lower — see the student loan table above.
How much is £60,000 a year per hour after tax?
On a standard 37.5-hour week (1,950 paid hours a year), £60,000 gross is £30.77 an hour, and your take-home works out at about £23.26 an hour.
How much National Insurance do I pay on £60,000?
Yes — 8% on earnings between £12,570 and £50,270, then 2% on everything above that. On £60,000 that comes to £3,211 a year. Employer NI (15%) is paid on top by your employer, not you.
How much student loan comes out of a £60,000 salary?
It depends on your plan. On Plan 1 (threshold £26,900) you repay 9% of earnings above it; on Plan 2 (threshold £29,385) the same rate applies above a higher bar. The table above shows the exact deduction for all five plans, including the 6% postgraduate rate.
Is £60,000 after tax different in Scotland?
Yes, and the gap widens with income. Scotland's bands run 19/20/21/42/45/48% versus UK-wide 20/40/45, and the higher rates kick in at lower thresholds. At this salary expect Scottish take-home to be a few pounds a week lower. National Insurance is the same UK-wide.
What happens to my take-home if I get a pay rise from £60,000?
You are earning above the higher-rate threshold: from here, extra pay is taxed at 40% with 2% NI added, making the marginal rate 42%. Exact net gains for £1,000, £2,500, £5,000 and £10,000 increases are in the pay-rise table above.
Does a workplace pension change these figures?
Yes. The figures on this page assume no pension contributions. Auto-enrolment pension contributions come out of pre-tax pay, so paying the minimum 5% cuts your take-home by less than 5% because you save income tax and NI on the sacrifice. Use the UK salary calculator to model your exact contribution.
Every figure here is built on the 2026/27 HMRC framework: a £12,570 tax-free personal allowance (tapered away above £100,000), income tax at 20/40/45%, and employee NI at 8% up to £50,270, then 2%. Student loan thresholds match the 2026/27 plan rates. For financial decisions, double-check with a qualified professional.
Related pages
UK salary calculator · £58,000 After Tax UK · £63,000 After Tax UK · Student loan repayments · US take-home pay by state · Average salary Ireland