Second Home Stamp Duty in 2026: Rates, Surcharge & Examples
Rates verified against HMRC SDLT tables · October 2026
A £300,000 second home costs £20,000 in stamp duty, not £5,000 — the 5% surcharge applies to the whole price. Here are the exact rates and worked examples.
Open the stamp duty calculatorSecond-home stamp duty rates 2026 (England & NI)
| Property price slice | Second-home rate (band + 5% surcharge) |
|---|---|
| £0 – £125,000 | 5% |
| £125,000 – £250,000 | 7% |
| £250,000 – £925,000 | 10% |
| £925,000 – £1,500,000 | 15% |
| Over £1,500,000 | 17% |
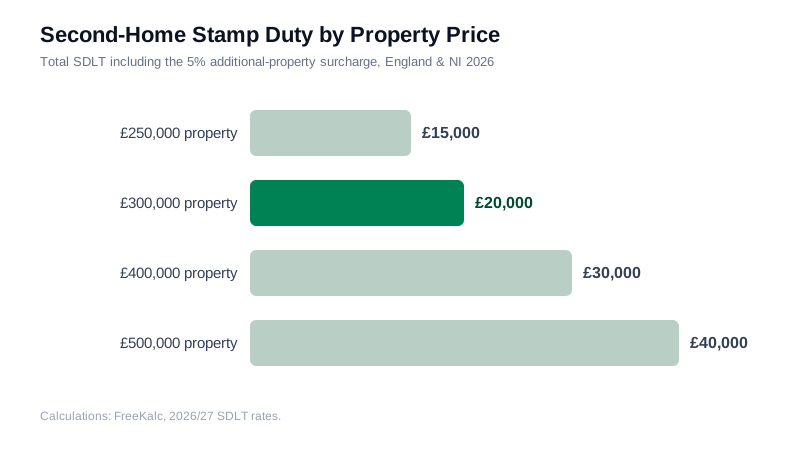
The surcharge applies to the entire price, not just the slice above your main home's value — that is why a second property is so much more expensive in tax terms.
Worked examples: second homes vs standard buys
| Price | Standard buyer | Second-home buyer | Extra cost |
|---|---|---|---|
| £250,000 | £2,500 | £15,000 | +£12,500 |
| £300,000 | £5,000 | £20,000 | +£15,000 |
| £400,000 | £10,000 | £30,000 | +£20,000 |
| £500,000 | £15,000 | £40,000 | +£25,000 |
When the surcharge does NOT apply
- You are replacing your main home and sell your old one within 3 years (or before the purchase completes)
- The property is worth under £40,000 (caravans, some mobile homes)
- You inherit the property
- A divorce or separation settlement transfers the home to you
Replacing your main home: the 3-year refund rule
If you buy a new main home before selling the old one, you pay the surcharge upfront — but you can claim a refund from HMRC if you sell the previous main home within 3 years of the new purchase. Around a third of surcharge payments are later refunded this way.
Replacing a main residence triggers a refund of the surcharge if you sell the previous home within 3 years of the purchase. The rules for additional properties are published by HMRC on gov.uk.
Frequently asked questionsDo I pay the second home surcharge on a buy-to-let?
Yes. The 5% additional-property surcharge applies to buy-to-let purchases and any second dwelling in England or Northern Ireland, on top of the normal band rates from the first pound.
How much is stamp duty on a £300,000 second home?
£20,000: the standard £5,000 (2% on £125,000–£250,000 plus 5% on £250,000–£300,000) plus a 5% surcharge (£15,000) on the full £300,000.
Can I get the surcharge refunded if I sell my main home?
Yes. If you are replacing your main home, you can claim a refund of the surcharge if you sell your previous main home within 3 years of the new purchase.
Does the surcharge apply in Scotland and Wales?
They have their own systems: Scotland charges the Additional Dwellings Supplement and Wales charges higher Land Transaction Tax rates on additional properties. This page covers England and Northern Ireland SDLT.
Do I pay the surcharge if I inherit a property?
No. Inherited properties do not trigger the additional-property surcharge, but the inherited home counts as an owned property when you next buy, which can push a later purchase into the higher rates.
Is a buy-to-let purchase charged the second-home surcharge?
Yes — an additional residential property, including a rental, attracts the surcharge. On a £300,000 buy-to-let the SDLT is £20,000, the same as any second home.
Can I get the surcharge refunded after buying?
Yes, if you bought a new main home before selling the old one and the sale completes within three years. The refund reclaims the 5% surcharge portion of the bill — it is claimed from HMRC, not issued automatically.
The buy-to-let angle: what landlords price in
Most second-home purchases are buy-to-let, and the surcharge is a business cost that has to earn its way back. On a £400,000 rental, the £30,000 SDLT is 7.5% of the purchase price before fees — money that typically has to be recovered through years of rental yield, which is why landlords price the tax into the offer from the first viewing. The refund rule matters most to this crowd: an investor who sells the previous main residence within three years of buying the new one can reclaim the surcharge, and the refund applies per property, not per person. The exceptions list is worth reading twice — inherited properties and transfers under £40,000 escape the charge, but a holiday let bought alongside a family home does not, no matter how it is used.
Related pages
- Stamp Duty Calculator — check any price instantly
- First-Time Buyer Stamp Duty Relief 2026
- Stamp Duty Rates 2026: full band tables
- Mortgage Payment Calculator
Sources: gov.uk SDLT rates and HMRC. Rates last verified October 2026. Estimates only — see our editorial policy.