How much is £150,000 a year after tax in the UK?
| Pay period | Take-home pay |
|---|---|
| Per year | £91,286.40 |
| Per month | £7,607.20 |
| Every 4 weeks | £7,022.03 |
| Per week | £1,755.51 |
| Per day (260 working days) | £351.10 |
| Per hour (37.5-hour week) | £46.81 |
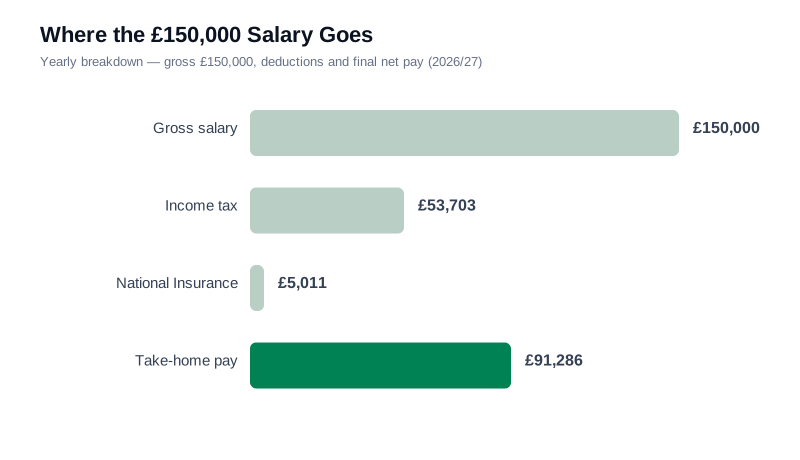
From £150,000 gross, you keep £91,286.40 — about 61% of everything you earn. The rest goes to income tax (£53,703) and National Insurance (£5,011).
Where does the money go — tax, NI and take-home?
| Deduction | Amount per year |
|---|---|
| Gross salary | £150,000.00 |
| Personal allowance | £0.00 tax-free (tapered above £100,000) |
| Income tax (20%/40% bands, reduced allowance) | −£53,703.00 |
| National Insurance (8% to £50,270, then 2%) | −£5,010.60 |
| Take-home pay | £91,286.40 |
You are above the additional-rate threshold: every extra pound is taxed at 45% plus 2% NI — a combined 47% marginal rate.
Student loan deductions on 150k: all five plans
Student loan repayments come out after tax and NI, on top of the deductions above. Which plan you are on changes your monthly pay at this salary level:
| Plan | Repayment threshold | Rate | Annual deduction |
|---|---|---|---|
| Plan 1 | £26,900.00 | 9% | £11,079.00 |
| Plan 2 | £29,385.00 | 9% | £10,855.35 |
| Plan 4 | £33,795.00 | 9% | £10,458.45 |
| Plan 5 | £25,000.00 | 9% | £11,250.00 |
| Postgraduate | £21,000.00 | 6% | £7,740.00 |
Plan 5 (£25,000) and postgraduate loans (£21,000) trigger repayments at the lowest incomes. Scottish Plan 4 loans only start above £33,795. Borrowers carrying both Plan 1 and Plan 2 repay both plans after crossing the Plan 1 threshold.
What a pay rise actually pays you
Below are the real amounts you would keep from common pay rises at this salary, using the 2026/27 bands, allowance taper and both NI rates:
| Pay rise | Tax + NI on the rise | Extra take-home |
|---|---|---|
| +£1,000 (to £151,000) | −£470.00 | +£530.00 net |
| +£2,500 (to £152,500) | −£1,175.00 | +£1,325.00 net |
| +£5,000 (to £155,000) | −£2,350.00 | +£2,650.00 net |
| +£10,000 (to £160,000) | −£4,700.00 | +£5,300.00 net |
From a £2,500 rise you keep about £110.42 extra each month, with your next pound taxed at 47%.
Monthly budget on 150k: the 50/30/20 rule
A common budgeting split for a take-home of £7,607.20 a month:
| Category | Share | Monthly amount | Typical use |
|---|---|---|---|
| Needs | 50% | £3,803.60 | Rent, utilities, food, transport, minimum debt payments |
| Wants | 30% | £2,282.16 | Dining out, streaming, gym, hobbies, travel |
| Savings & debt payoff | 20% | £1,521.44 | Emergency fund, pension top-ups, overpaying debt |
Mortgage lenders typically cap borrowing near 4.5× gross salary, so a 150k income supports roughly a £675,000 mortgage — enough for a first flat in most regional cities with a 10% deposit.
What about Scotland?
Scottish income tax uses different bands — a 19% starter rate, then 20%, then a 21% intermediate rate, with higher rates of 42% and 45% (48% on income above £75,000). At this salary the gap is a few pounds a week, growing with income. National Insurance is the same UK-wide.
Does a pension change this?
The figures above assume no pension contributions. Auto-enrolment takes a minimum 5% of your salary pre-tax, but because contributions reduce taxable pay the hit to take-home is only about £450.00 a month at the 5% minimum — and your employer adds at least 3% on top. Above £100,000, salary-sacrifice contributions also reduce adjusted net income and can restore tapered personal allowance — often the single best financial move at this salary.
Is 150k a good salary in the UK?
£150,000 puts you in roughly the top 1-2% of UK full-time earners — your personal allowance is gone entirely, and income above £125,140 is taxed at the 45% additional rate.
£7,607 a month is top-1-2% money: the constraints are lifestyle choices, not budget. Note that every extra pound is now taxed at 47% (45% additional rate plus 2% NI) — plus 9% student loan if you still have one.
Frequently asked questions
Is £150,000 a year a good salary in the UK in 2026?
£150,000 puts you in roughly the top 1-2% of UK full-time earners — your personal allowance is gone entirely, and income above £125,140 is taxed at the 45% additional rate. Against a median of about £37,430, this is well above the typical UK wage.
How much is £150,000 a year per month after tax?
Take-home pay is £91,286.40 a year, which is £7,607.20 per month after income tax and National Insurance. With a student loan the figure is lower — see the student loan table above.
How much is £150,000 a year per hour after tax?
On a standard 37.5-hour week (1,950 paid hours a year), £150,000 gross is £76.92 an hour, and your take-home works out at about £46.81 an hour.
How much National Insurance do I pay on £150,000?
Yes — 8% on earnings between £12,570 and £50,270, then 2% on everything above that. On £150,000 that comes to £5,011 a year. Employer NI (15%) is paid on top by your employer, not you.
How much student loan comes out of a £150,000 salary?
Your plan decides it. Plan 1 deducts 9% of earnings above £26,900; Plan 2 applies the same 9% but only once you earn over £29,385. Exact monthly deductions for every plan — including the 6% postgraduate rate — are in the table above.
Is £150,000 after tax different in Scotland?
Yes, and the gap widens with income. Scotland's bands run 19/20/21/42/45/48% versus UK-wide 20/40/45, and the higher rates kick in at lower thresholds. At this salary expect Scottish take-home to be a few pounds a week lower. National Insurance is the same UK-wide.
What happens to my take-home if I get a pay rise from £150,000?
You are above the additional-rate threshold: every extra pound is taxed at 45% plus 2% NI — a combined 47% marginal rate. The pay-rise table above shows the exact net gain for £1,000, £2,500, £5,000 and £10,000 increases.
Does a workplace pension change these figures?
Yes — and above £100,000 it matters twice over. Contributions come out of pre-tax pay, and salary-sacrifice pension contributions also reduce your adjusted net income, which can restore some of the tapered personal allowance. Many higher earners deliberately pension-salary-sacrifice down toward £100,000 for exactly this reason. Use the UK salary calculator to model your exact contribution.
Estimates use 2026/27 HMRC rates: £12,570 personal allowance (tapered above £100,000), 20/40/45% bands, 8% employee NI to £50,270 then 2%. Student loan thresholds follow the 2026/27 plan rates. Always confirm with a qualified professional for financial decisions.
Related pages
UK salary calculator · £120,000 After Tax UK · Student loan repayments · US take-home pay by state · Average salary Ireland