How Much Is Stamp Duty on a £250,000 House?
Rates verified against HMRC SDLT tables · October 2026
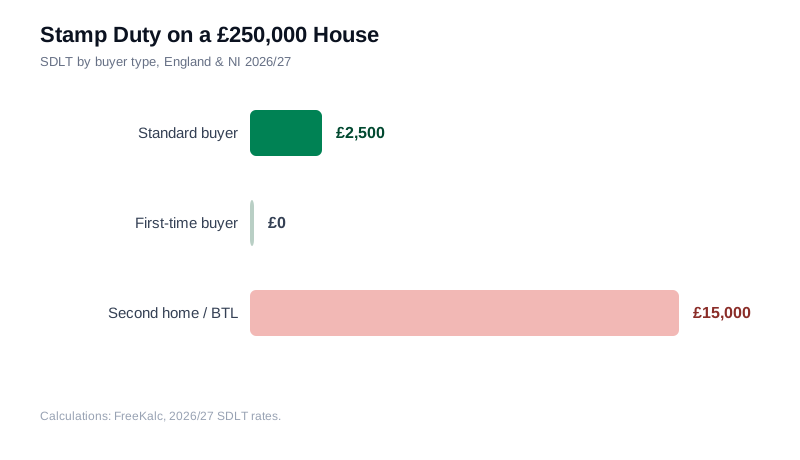
Stamp duty on a £250,000 house in England or Northern Ireland is £2,500 for a standard buyer — an effective rate of 1.00% on the whole price. First-time buyers pay £0 under the first-home relief, and second-home or buy-to-let buyers pay £15,000 because of the 5% additional-property surcharge.
SDLT is charged slice by slice, like income tax: only the portion of the price inside each band pays that band's rate. On a £250,000 property the whole bill comes from the 2% slice between £125,000 and £250,000 — so This is a typical price in Greater Manchester, Merseyside, Yorkshire and the North East.
Stamp duty on a £250k house at a glance
| Buyer type | Stamp duty | Effective rate |
|---|---|---|
| Standard buyer | £2,500 | 1.00% |
| First-time buyer | £0 | 0.00% |
| Second home / buy-to-let | £15,000 | 6.00% |
Why it is £2,500: the slice-by-slice bands
SDLT never charges one rate on the whole price. Instead, the £250,000 is split into slices, and each slice pays only its own rate:
| Price slice | Rate | Tax on slice |
|---|---|---|
| £125,000 – £250,000 | 2% | £2,500 |
| Total | — | £2,500 |
The bands for 2026/27 are: 0% to £125,000, 2% to £250,000, 5% to £925,000, 10% to £1.5 million and 12% above that. Because a £250,000 home never leaves the 2% band, the bill stays at £2,500.
Stamp duty at £250,000 by buyer type — and at nearby prices
The headline figure for a £250,000 purchase is £2,500 at standard rates — an effective rate of 1.00%. But the bill depends on who is buying. A first-time buyer pays £0 thanks to relief on the first £300,000, while anyone buying an additional property pays £15,000 once the 5% surcharge is added. The tables below use the same England and Northern Ireland rates as the calculator on this page.
| Buyer type | Stamp duty | Effective rate | Price + duty |
|---|---|---|---|
| Standard (main residence) | £2,500 | 1.00% | £252,500 |
| First-time buyer | £0 | 0.00% | £250,000 |
| Additional property (second home / buy-to-let) | £15,000 | 6.00% | £265,000 |
| Purchase price | Standard stamp duty | Effective rate | Additional-property duty |
|---|---|---|---|
| £125,000 | £0 | 0.00% | £6,250 |
| £150,000 | £500 | 0.33% | £8,000 |
| £175,000 | £1,000 | 0.57% | £9,750 |
| £200,000 | £1,500 | 0.75% | £11,500 |
| £225,000 | £2,000 | 0.89% | £13,250 |
| £250,000 | £2,500 | 1.00% | £15,000 |
| £275,000 | £3,750 | 1.36% | £17,500 |
| £300,000 | £5,000 | 1.67% | £20,000 |
| £325,000 | £6,250 | 1.92% | £22,500 |
| £350,000 | £7,500 | 2.14% | £25,000 |
| £375,000 | £8,750 | 2.33% | £27,500 |
At £250,000 the marginal rate is 5%, so every extra £1,000 on the price adds £50 of standard-rate duty. Negotiating £10,000 off the price would save £500 in tax at this level.
First-time buyers and second homes at £250k
First-time buyer relief
First-time buyer relief makes the bill exactly £0 — £250,000 is fully inside the 0%-to-£300,000 relief zone, so nothing is payable. The relief applies only to a genuine first home: you must never have held a freehold or leasehold property anywhere in the world, and if you are buying jointly every named buyer must qualify.
The additional-property surcharge
The 5% surcharge applies to the whole £250,000, stacking £12,500 on top of the standard £2,500. The surcharge applies to the entire price from the first pound — not just the difference between properties — which is why second homes carry such a heavy effective rate of 6.0%.
How a £250k house compares with nearby prices
The slice-by-slice system means the bill moves unevenly: small price rises barely register inside a band, then jump at every band edge. Here is the exact duty at prices around £250,000:
| Property price | Standard | First-time buyer | Second home |
|---|---|---|---|
| £200,000 | £1,500 | £0 | £11,500 |
| £225,000 | £2,000 | £0 | £13,250 |
| £250,000 | £2,500 | £0 | £15,000 |
| £275,000 | £3,750 | £0 | £17,500 |
| £300,000 | £5,000 | £0 | £20,000 |
Use this when negotiating: at this level every £5,000 change in the agreed price moves the standard bill by about £100, and the second-home bill by about £350.
What the £2,500 bill means in practice
Stamp duty is due within 14 days of completion and is normally paid through your conveyancer. At £250,000, the £2,500 bill is small enough that it rarely changes buying decisions — and negotiating the price matters: every £10,000 off at this level saves plus ££200 in duty.
Scotland (LBTT) and Wales (LTT) use entirely different tax systems with different bands — the figures on this page apply to England and Northern Ireland only.
Frequently asked questions
How much is stamp duty on a £250k house?
A standard buyer in England or Northern Ireland pays £2,500 on a £250,000 property — an effective rate of 1.00% across the whole price. First-time buyers pay £0 and additional-property buyers pay £15,000.
What do first-time buyers pay on a £250k house?
£0. First-time buyer relief makes the bill exactly £0 — £250,000 is fully inside the 0%-to-£300,000 relief zone, so nothing is payable.
What do second-home and buy-to-let buyers pay on a £250k house?
£15,000. The 5% surcharge applies to the whole £250,000, stacking £12,500 on top of the standard £2,500.
£250,000 is called a band edge — what does that mean?
It is the top of the 2% band. At exactly £250,000 you pay 2% on the £125,000–£250,000 slice (£2,500). The very next pound is taxed at 5%, so a £251,000 house costs £2,550 — the marginal rate more than doubles.
When do I have to pay stamp duty on a £250k purchase?
Within 14 days of completion. Since March 2019 the filing and payment deadline is 14 days, down from 30. Your conveyancer usually files the SDLT return for you, but the legal responsibility to pay on time is yours.
What is the effective stamp duty rate on a £250k house?
1.00% of the purchase price for a standard buyer (£2,500 on £250,000). The marginal rate on your next pound is higher — 5% once the price passes £250,000 — because SDLT is charged slice by slice, like income tax.
Can I reduce stamp duty by separating fixtures and fittings?
Only for genuinely removable items. Carpets, curtains, white goods and free-standing furniture can be apportioned separately from the property price in the SDLT return — but fixtures like kitchens, bathrooms and fitted wardrobes cannot. HMRC challenges inflated apportionments, and the amounts must reflect real market values.
Is stamp duty different in Scotland and Wales?
Yes. Scotland charges Land and Buildings Transaction Tax (LBTT) and Wales charges Land Transaction Tax (LTT) — each has its own bands, thresholds and reliefs, and this page's figures apply to England and Northern Ireland only.
Related pages
- Stamp duty calculator — work out any price instantly
- How much is stamp duty on a £200k house?
- How much is stamp duty on a £300k house?
- SDLT rate bands — the full 2026/27 table
- First-time buyer relief — the £300,000/£500,000 rules in full
- Second-home surcharge — the 5% extra in detail