Mortgage borrowing on a £22,000 salary at a glance
| Income multiple | Max borrowing | Monthly payment (25yr, 4.5%) |
|---|---|---|
| 4x income (conservative) | £88,000 | £489 |
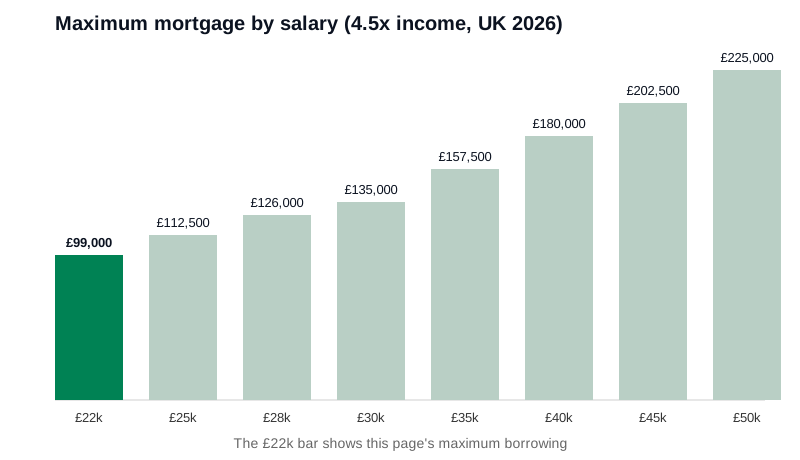
| 4.5x income (typical max) | £99,000 | £550 |
| 5x income (some lenders, higher earners) | £110,000 | £611 |
What that means in practice
Borrowing £88,000 at 4x income supports a property of about £97,778 with a 10% deposit of £9,778. Lenders check the monthly payment against your spending too, not just the multiple — at about £489 a month the payment sits near a third of a typical £22,000 take-home, which is inside most affordability models.
Monthly payments on £88,000 over 25 years: £464 at 4%, £489 at 4.5%, £514 at 5%. A bigger deposit moves you to a lower LTV band and cheaper rates. The MoneyHelper mortgage calculator is the official independent tool for checking affordability on gov-backed guidance.
What lenders actually check on a £22,000 salary
A lender reading a £22,000 application is usually reading a short credit history — first full-time job, a rented address, a young file. The income multiple matters less at this level than the shape of the earnings: lenders want a permanent contract or 12+ months of consistent payslips, and they discount probation periods and irregular overtime. Three preparation moves reliably strengthen the file: register on the electoral roll at your current address (a fast, free credibility boost), drop every credit card balance below 30% of its limit for three months before applying, and keep the bank statements boring — no unexplained cash deposits, no gambling activity, no overdraft spirals in the assessment window. Lenders also check that the salary is sustainable: a £22,000 income with two years of history beats a recent jump with no payslips behind it.
£22,000: the starter salary and the joint-application reality
On £22,000, the solo borrowing band of £88,000–£99,000 is the honest starting point — and for most buyers at this income the realistic route runs through two doors. The first is the joint application: two incomes are multiplied together, so a £22,000 salary alongside a partner’s £28,000 typically unlocks the borrowing of a £50,000 household, not a £22,000 one. The second is shared ownership: buying a 25–50% share of a property shrinks the mortgage to fit the band, with rent paid on the remainder and the option to staircase later. Both routes reward the same preparation — a clean credit file, evidence of consistent earnings and a deposit built in a Lifetime ISA where the 25% government bonus quietly adds 25p to every £1 saved.
Frequently asked questions
How much mortgage can I get on a £22,000 salary?
The mainstream maths: 4–4.5 times a £22,000 income points to £88,000–£99,000. Treat that as the ceiling, then let the affordability check do its trimming — commitments and childcare come off before the lender quotes.
What mortgage can I afford on a £22,000 salary?
Start from the payment, not the salary. £88,000 over 25 years costs roughly £489 a month at 4.5% — and if that fits your budget after rent-free living, most affordability models agree with the band.
How much mortgage can you get with a 22000 annual salary?
Around £88,000–£99,000 from mainstream lenders: £88,000 at a conservative 4x, £99,000 at the common 4.5x. Joint applications and shared ownership open wider doors than stretching the solo multiple.
What deposit do I need with a £22,000 salary?
On a £97,778 starter property (the 4x scenario), a 10% deposit is £9,778. A Lifetime ISA accelerates it: every £4,000 saved adds £1,000 of government money to the deposit.
What are the monthly payments on a £22,000 salary mortgage?
£88,000 over 25 years prices at about £464 (4%), £489 (4.5%) and £514 (5%) a month. A longer term or bigger deposit trims the figure the affordability model judges.
Can a £22,000 and £28,000 salary get a mortgage together?
Yes — most lenders apply the income multiple to the combined household income. On £50,000 combined, the 4–4.5x band points to roughly £200,000–£225,000 before affordability checks trim it.
Is shared ownership realistic on £22,000?
Often, yes. You mortgage only the share you buy, so the loan matches a fraction of the property price — and you can buy bigger shares later as your income grows.
Is £88,000 the absolute maximum on £22,000?
No. The band reflects the common 4–4.5x multiples; specialist lenders can stretch toward 5x for strong applications, while affordability checks can also trim the band down.
Related pages
- Mortgage calculator — payments on any loan size
- How much mortgage can I afford? — the full UK guide
- Average UK salary — see where £22,000 sits nationally
- Mortgage on a £25,000 salary
- Mortgage on a £28,000 salary
- Mortgage on a £30,000 salary
- Mortgage on a £35,000 salary
- Mortgage on a £40,000 salary
- Mortgage on a £45,000 salary
- Mortgage on a £50,000 salary