Mortgage borrowing on a £35,000 salary at a glance
| Income multiple | Max borrowing | Monthly payment (25yr, 4.5%) |
|---|---|---|
| 4x income (conservative) | £140,000 | £778 |
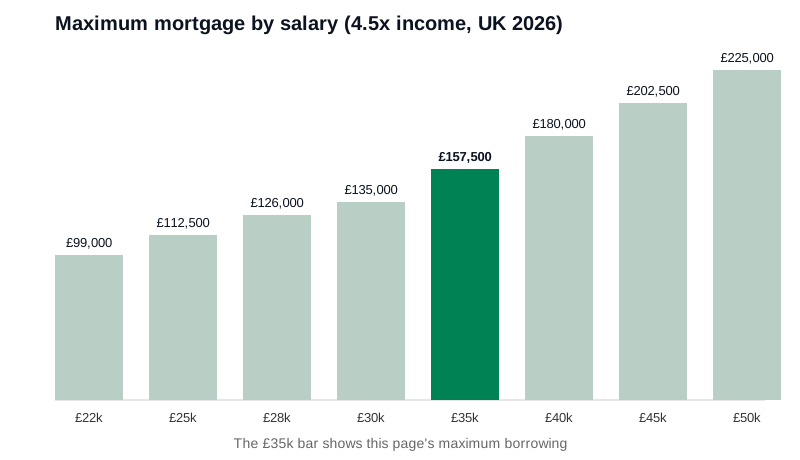
| 4.5x income (typical max) | £157,500 | £875 |
| 5x income (some lenders, higher earners) | £175,000 | £973 |
What that means in practice
Borrowing £140,000 at 4x income supports a property of about £155,556 with a 10% deposit of £15,556. Lenders check the monthly payment against your spending too, not just the multiple — at about £778 a month the payment sits near a third of a typical £35,000 take-home, which is inside most affordability models.
Monthly payments on £140,000 over 25 years: £739 at 4%, £778 at 4.5%, £818 at 5%. A bigger deposit moves you to a lower LTV band and cheaper rates. The MoneyHelper mortgage calculator is the official independent tool for checking affordability on gov-backed guidance.
What lenders actually check on a £35,000 salary
At £35,000 lenders treat the file as a solid single income — and the checks shift toward earnings quality. Variable components matter most: overtime, commission and bonus count only with a provable pattern (usually twelve months of payslips with the employer confirming the arrangement in writing), and a guaranteed £35,000 is worth more to the calculation than an erratic £38,000. The affordability model still does its subtraction — childcare and committed debts — but a clean £35,000 file typically quotes from the top of the 4–4.5x band rather than the middle. Where joint applications are involved, the lender assesses both credit files, and the weaker of the two can drag the whole application: errors, missed registrations or an unresolved dispute on the partner’s file cost more at this level than at any other, because the combined band is worth enough to fight for.
£35,000: above the average — and what it changes
An income of £35,000 clears the UK individual average, and the borrowing band of £140,000–£157,500 moves a buyer from the entry tier to the mainstream market. What changes at this level is options, not just amounts. The 5% deposit deals become comfortably serviceable rather than a stretch. Two-bedroom homes in the Midlands and North enter reach outright, and the South East commuter belt opens at the flat end. The joint-application arithmetic also strengthens sharply: £35,000 plus a partner’s £30,000 points most lenders at a combined £65,000 — a band approaching £292,000 before commitments trim it, the classic first-house budget for dual-income households.
Frequently asked questions
How much mortgage can I get on a £35,000 salary?
£140,000–£157,500 is the mainstream band on £35,000 (4–4.5x). Files this clean usually quote from the top — guaranteed income reads better than an erratic higher figure.
What mortgage can I afford on a £35,000 salary?
£140,000 of borrowing costs about £778 a month at 4.5% over 25 years. The affordability model deducts childcare and debts before it agrees with the multiple.
How much mortgage can you get with a 35000 annual salary?
High-street lenders typically offer £140,000 at 4x or £157,500 at 4.5x. Variable pay needs a provable pattern — the guaranteed part counts in full, the rest needs history.
What deposit do I need with a £35,000 salary?
The 4x scenario supports a £155,556 property, putting the 10% deposit at £15,556. A joint application with a £30,000 partner multiplies the household instead.
What are the monthly payments on a £35,000 salary mortgage?
£140,000 over 25 years prices at about £739 (4%), £778 (4.5%), £818 (5%) monthly. Deposit size decides the rate tier; the term decides the payment.
What can a £35,000 plus £30,000 couple borrow?
On combined income of £65,000, the 4–4.5x band points to roughly £260,000–£292,000 before the affordability checks apply their deductions.
Does a £35,000 salary get better mortgage rates?
Not directly — rates follow deposit size and loan-to-value. But a stronger income supports a bigger deposit faster, and it passes the stress test with more headroom.
Is it worth waiting for a raise before applying on £35,000?
If the raise is documented and near, yes — lenders multiply the salary the payslips show. If it is speculative, apply on today’s figure and remortgage later.
Related pages
- Mortgage calculator — payments on any loan size
- How much mortgage can I afford? — the full UK guide
- Average UK salary — see where £35,000 sits nationally
- Mortgage on a £22,000 salary
- Mortgage on a £25,000 salary
- Mortgage on a £28,000 salary
- Mortgage on a £30,000 salary
- Mortgage on a £40,000 salary
- Mortgage on a £45,000 salary
- Mortgage on a £50,000 salary