Mortgage borrowing on a £28,000 salary at a glance
| Income multiple | Max borrowing | Monthly payment (25yr, 4.5%) |
|---|---|---|
| 4x income (conservative) | £112,000 | £623 |
| 4.5x income (typical max) | £126,000 | £700 |
| 5x income (some lenders, higher earners) | £140,000 | £778 |
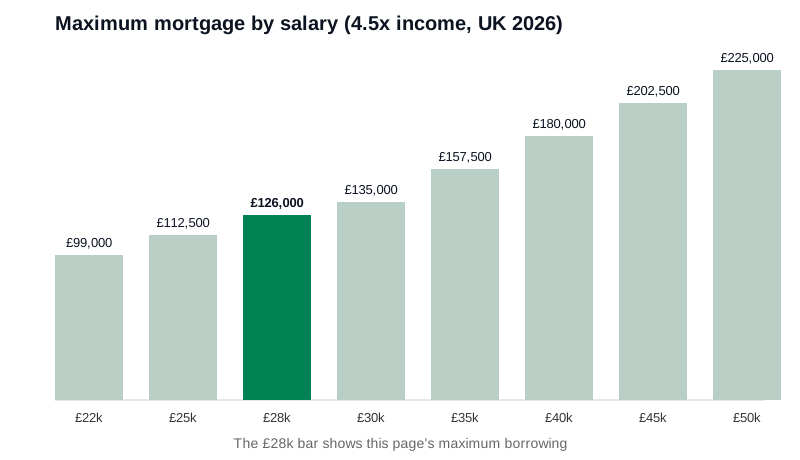
What that means in practice
Borrowing £112,000 at 4x income supports a property of about £124,444 with a 10% deposit of £12,444. Lenders check the monthly payment against your spending too, not just the multiple — at about £623 a month the payment sits near a third of a typical £28,000 take-home, which is inside most affordability models.
Monthly payments on £112,000 over 25 years: £591 at 4%, £623 at 4.5%, £655 at 5%. A bigger deposit moves you to a lower LTV band and cheaper rates. The MoneyHelper mortgage calculator is the official independent tool for checking affordability on gov-backed guidance.
What lenders actually check on a £28,000 salary
A £28,000 application reads as the textbook mainstream file, so lenders check it in textbook order: contract and probation status first, then commitments, then deposit source. Two earners change the arithmetic — for joint applications the lender assesses the combined £56,000 (or whatever the second income adds), and the stronger file is the one that documents both salaries cleanly, including the second applicant’s probation clauses and any career-break gaps with dates and evidence. Single applicants at this level get the full stress test treatment: the lender models a rate several points above today’s and subtracts childcare, commuting and debt minimums from the budget before quoting. The files that pass smoothly are the ones with plain-sailing bank statements for the last three months — regular saving, no payday lending, no unexplained deposits over the source-of-funds threshold.
£28,000: the near-average earner’s playbook
£28,000 sits just under the UK individual median, and the borrowing band of £112,000–£126,000 tells a familiar story: enough for a solid flat in much of the country, not enough to go solo in the expensive South. The playbook that works here is arithmetic, not luck. A second income multiplies the band — two £28,000 salaries point most lenders at the combined £56,000, not two separate bands. A longer mortgage term lowers the monthly payment the affordability check measures against, buying headroom without changing the salary. And a promotion timed before application matters: lenders work from the salary the payslips show, so a raise documented before applying moves the band in a way no negotiation at the estate agent can.
Frequently asked questions
How much mortgage can I get on a £28,000 salary?
Two salaries multiply: solo, £28,000 points to £112,000–£126,000 at 4–4.5x. Combined with a partner’s, the household income sets the band instead.
What mortgage can I afford on a £28,000 salary?
Affordability runs on the monthly figure — £623 a month on £112,000 at 4.5% over 25 years. The lender stress-tests that payment, not your job title.
How much mortgage can you get with a 28000 annual salary?
Mainstream lenders quote £112,000 (4x) to £126,000 (4.5x) on a £28,000 income. A documented raise before applying moves the band more than any negotiation after.
What deposit do I need with a £28,000 salary?
The 4x scenario prices a £124,444 property, so 10% is £12,444. Bank-statement hygiene in the three months before application matters as much as the amount.
What are the monthly payments on a £28,000 salary mortgage?
£112,000 over 25 years costs about £591 (4%), £623 (4.5%) or £655 (5%) a month. Term length is the lever most £28,000 applicants forget to pull.
Can two £28,000 salaries borrow more than twice £126,000?
Not twice — but lenders apply the multiple to the combined £56,000, which points toward £224,000–£252,000 before stress tests and commitments trim it.
Does a 35-year term help on a £28,000 salary?
Yes — it lowers the monthly payment, which is what the affordability check measures. The trade-off is more interest over the life of the loan.
What can £126,000 actually buy in the UK?
In much of the North, Wales and Scotland: a one- or two-bedroom flat outright. In the South East, a share through shared ownership. The page’s own table shows the regional reality.
Related pages
- Mortgage calculator — payments on any loan size
- How much mortgage can I afford? — the full UK guide
- Average UK salary — see where £28,000 sits nationally
- Mortgage on a £22,000 salary
- Mortgage on a £25,000 salary
- Mortgage on a £30,000 salary
- Mortgage on a £35,000 salary
- Mortgage on a £40,000 salary
- Mortgage on a £45,000 salary
- Mortgage on a £50,000 salary